
OCC rewrites bank enforcement rules to make supervision softer and more predictable
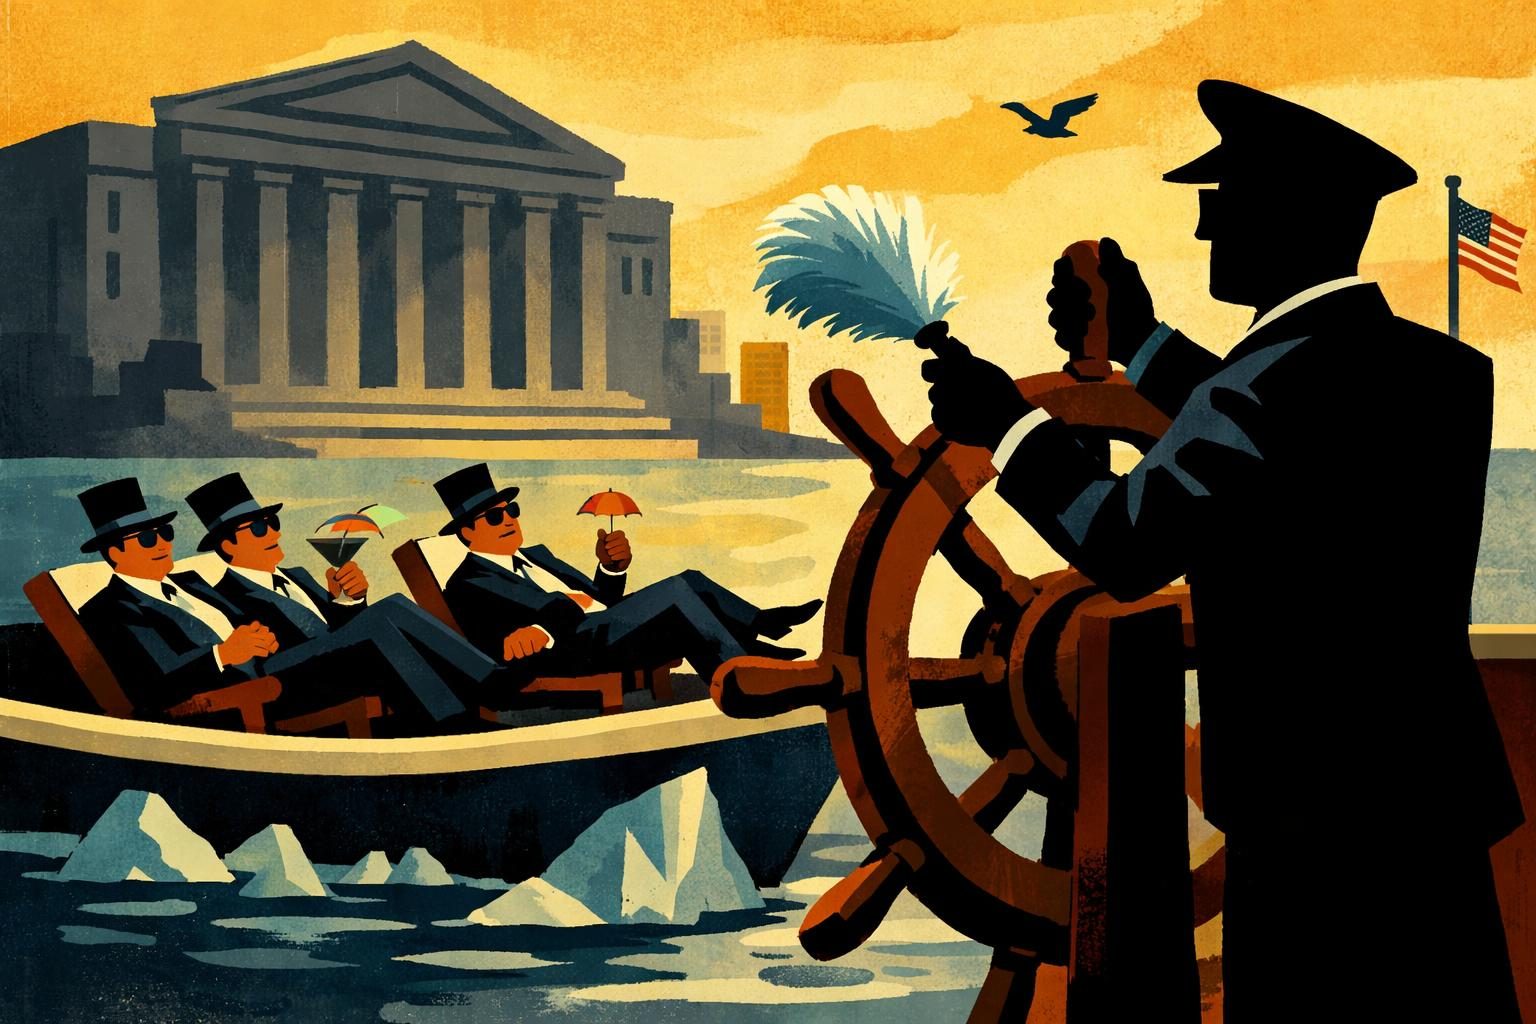
The Office of the Comptroller of the Currency moved on August 27 to recast how it handles bank enforcement and supervision, saying it is codifying a more risk-based approach that it says should make its standards clearer, more consistent, and easier to understand. In plain English, the agency is trying to put a more deliberate frame around when and how it presses banks, rather than leaving the process to what critics would describe as a patchwork of judgment calls. The OCC presented the change as a technical refinement to supervision, but the choice of language matters because enforcement philosophy is never just paperwork. It shapes how examiners interpret problems, how quickly institutions feel pressure to fix them, and how much room large banks believe they have to negotiate when regulators show up with questions. In that sense, the announcement reads less like a housekeeping notice than a signal about how the agency wants to exercise authority going forward. The OCC’s message was not that it is abandoning oversight, but that it wants oversight to feel more structured and more predictable. That may sound harmless on its face, but in financial regulation predictability can be a double-edged word, especially when it begins to mean fewer surprises for the biggest firms.
The agency says the revisions are meant to improve transparency and consistency, two goals that are easy to defend and hard to argue against in the abstract. Bank supervision can be opaque even to people inside the system, and there is a genuine case for making expectations more legible so institutions know what is required of them. The problem is that “clarity” in enforcement often comes paired with a softer touch in practice, particularly when the new framework emphasizes risk-based judgment. That phrase sounds neutral, but its consequences depend entirely on how aggressively the regulator is willing to use it. If applied carefully, it can help direct limited resources toward the most dangerous problems. If applied loosely, it can become a convenient justification for stepping back from tougher intervention until a problem becomes too large to ignore. The OCC’s own framing suggests it wants to reserve the strongest responses for situations it views as most serious, while allowing more tailored treatment across different types of banks. That distinction may make sense on paper, especially if community banks and large complex banks really do present different levels of risk. Still, history offers plenty of reasons to be skeptical whenever a regulatory agency promises nuance in a system that has repeatedly turned nuance into deference for the largest players. The larger the institution, the more likely it is to have the lawyers, consultants, and negotiating leverage to turn flexible standards into an advantage.
That is why the political and policy significance of this move goes beyond the agency’s internal procedures. Enforcement standards are not merely a matter of supervision manuals or examiner training. They define the boundaries of acceptable conduct and the degree of urgency regulators bring to misconduct, weak controls, or other operational failures. A bank that believes oversight is becoming more predictable may also conclude that the consequences of delay, negotiation, or partial compliance are becoming easier to manage. That shift can alter how quickly institutions address problems and how willing they are to accept serious remediation without a fight. It can also affect the power balance between examiners and the firms they oversee, because enforcement is often as much about signaling as it is about formal action. When regulators appear willing to escalate, banks tend to move faster. When regulators appear more accommodating, the incentive to stall gets stronger. Progressive critics are likely to read the OCC’s decision as another example of the federal government smoothing the rough edges of accountability at a moment when public confidence in financial oversight is still fragile. They are likely to argue that a friendlier supervisory posture is not the same thing as stronger governance, even if it comes wrapped in better-sounding terminology. Supporters, by contrast, will probably say the agency is trying to match its tools to the actual level of risk and avoid one-size-fits-all pressure that can waste resources or discourage legitimate lending. Both readings are plausible, which is exactly what makes the announcement politically sensitive. The more discretion a regulator gives itself in the name of consistency, the more important it becomes to watch how that discretion is used in real cases rather than in the press release.
The practical fallout of the OCC’s shift may not show up in a dramatic single event. More likely, it will accumulate through a series of smaller judgments that determine how much leverage the agency has in day-to-day oversight. That includes how quickly examiners escalate concerns, how much room banks get to negotiate corrective actions, and how firmly the agency insists on changes before issues become larger problems. In a system as interconnected as banking, those choices can matter a great deal even when they are invisible to the public. A softer enforcement posture does not necessarily mean weaker supervision, but it does raise the burden on the OCC to prove that its new approach will still catch emerging risks early and act before damage spreads. If the agency is right, this is modernization: a cleaner framework, better-targeted pressure, and more disciplined supervision. If it is wrong, it risks becoming yet another case of regulators mistaking a friendlier tone for an effective one. Either way, the change reflects a broader truth about financial oversight that rarely gets stated plainly enough: the real test of regulation is not whether it sounds balanced, but whether it changes behavior where it counts. Banks will notice. So will watchdogs. And if the new framework does make supervision more predictable, the next question is whether predictable means more fair, or simply more comfortable for the institutions that already know how to work the system.
Comments
Threaded replies, voting, and reports are live. New users still go through screening on their first approved comments.
Log in to comment
No comments yet. Be the first reasonably on-topic person here.