
Bank regulators rewrite the rules on what counts as an enforcement problem
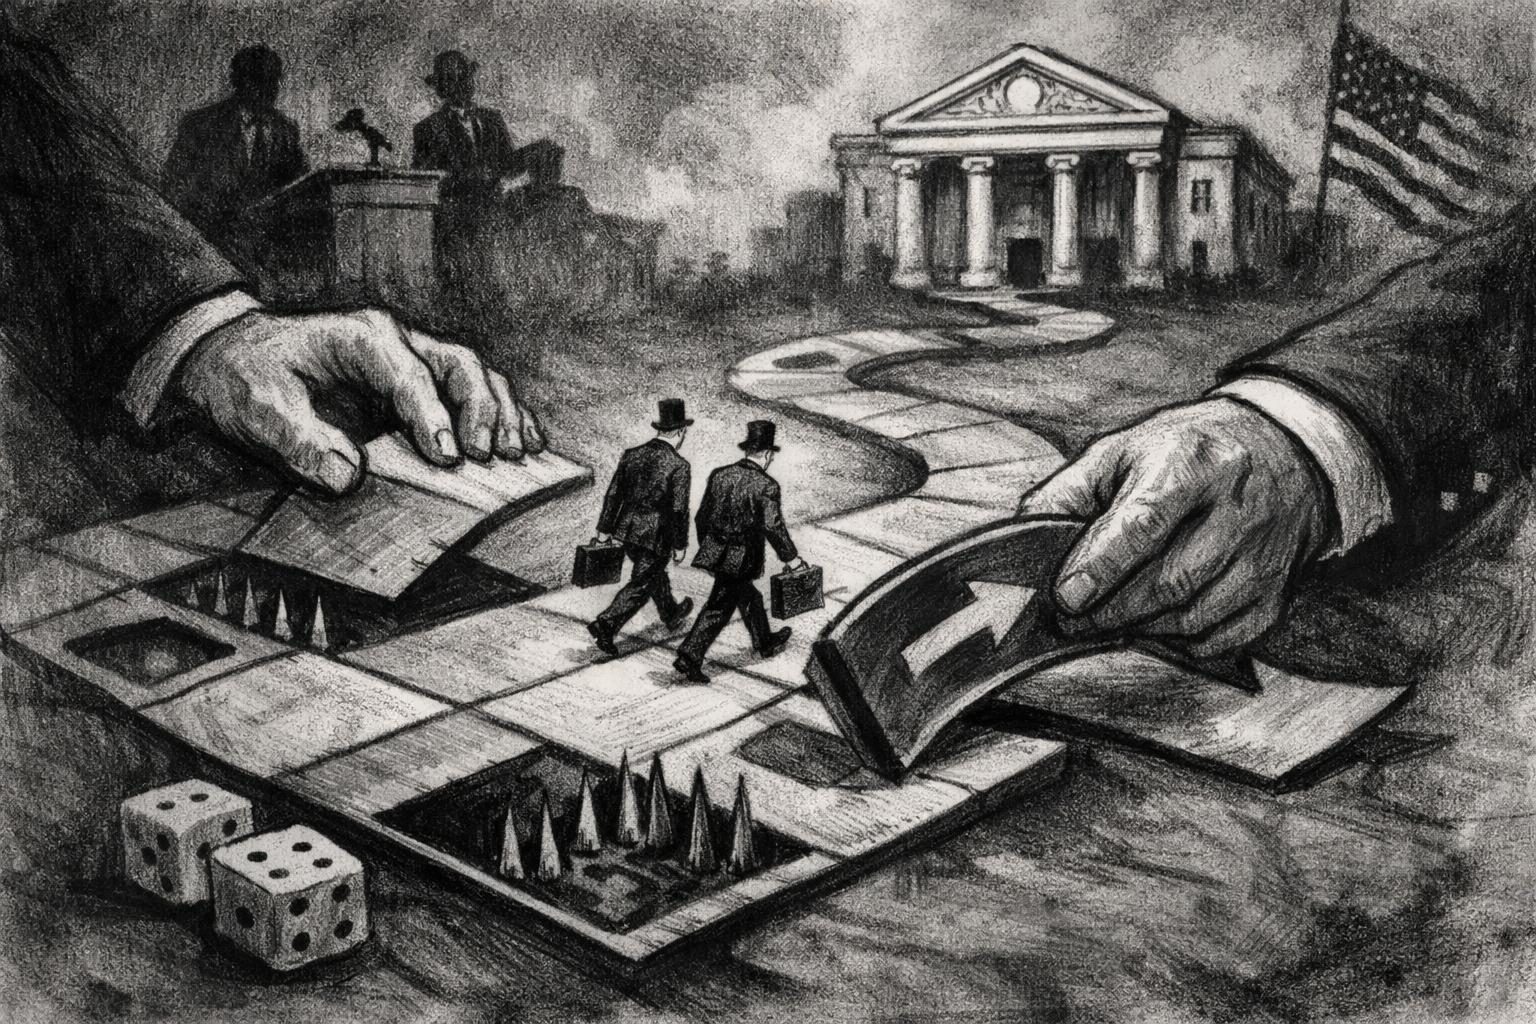
Federal bank regulators on Thursday moved to redraw the line between ordinary supervisory concern and the kind of problem that can trigger a more serious enforcement response, a shift that could have real consequences for how closely banks are watched and how quickly examiners move when trouble appears. The Office of the Comptroller of the Currency and the Federal Deposit Insurance Corporation announced a final rule and related policy changes aimed at bringing more clarity and consistency to the way they identify unsafe or unsound practices and matters requiring attention. On paper, the agencies say the new framework is supposed to make supervision more disciplined by focusing attention on material financial risks. In practice, that means the regulators are narrowing the spotlight to the issues they consider big enough to matter, while leaving smaller or less immediate problems more likely to be handled through softer supervisory tools. Supporters will describe that as a sensible cleanup of a process that can feel vague, uneven, and overly dependent on examiner judgment. Critics are likely to see something else: a gentler runway for banks that already know how to push the edges of the rules.
The agencies’ basic argument is straightforward enough. They want bank supervision to be clearer, more consistent, and less prone to drifting into open-ended enforcement over relatively minor issues that may not pose a genuine threat to a bank’s safety and soundness. That sounds technical because it is technical, but the technical details matter. What counts as a material risk, who gets to decide, and how much room examiners have to escalate a concern can determine whether a problem is dealt with early or allowed to harden into something much harder to fix. A bank with weak controls, sloppier risk management, or persistent compliance failures can sometimes survive for a long time if watchdogs only focus on the biggest red flags. At the same time, a system that treats every shortcoming as a major violation can become unpredictable and punitive, making it harder for institutions to know what regulators expect. The new standards appear to try to strike a balance between those two pressures, though any such balance is likely to be contested the moment the first large bank or troubled regional lender gets judged under the revised rules.
That tension is why the change is bigger than it first appears. Bank supervision is one of the quieter powers in Washington, but it shapes how financial risk gets managed long before a crisis reaches the public. If examiners are encouraged to reserve stronger action for only the most significant problems, the result could be a more focused and defensible process that avoids wasting time on technicalities. If, however, the standard ends up making supervisors hesitate before acting, banks with fragile controls may get more room to drift, and the warning signs that usually precede trouble may be easier to dismiss. The agencies are presenting the move as a way to improve consistency rather than as a retreat from oversight, and that distinction will matter in the coming debates. For banks, more predictability is welcome because it helps them plan, budget, and manage compliance. For depositors, consumers, and anyone who remembers how quickly financial problems can spread, predictability matters only if it still leaves regulators nimble enough to stop losses before they become systemic. That is the core policy tradeoff here, and it is not going away just because the rule language is cleaner.
The broader political backdrop also matters. The change fits into a larger pattern of financial governance under the current administration that favors formal rulemaking, narrower definitions, and a more restrained use of discretion in enforcement. Advocates of that approach argue that supervision has become too opaque and too dependent on case-by-case judgments that can feel arbitrary to the industry. They say clearer rules reduce uncertainty and stop regulators from moving the goalposts after the fact. But critics of the shift will likely argue that this kind of reform can work as deregulation with a better haircut: it sounds orderly, yet it can quietly lower the odds that examiners will press hard on emerging problems before those problems turn into losses for banks, households, or the deposit insurance system. The agencies are likely to insist the opposite, that they are restoring discipline and focusing scarce supervisory resources where they can do the most good. The disagreement is less about whether supervision should be rational than about how much damage the system can absorb before a concern becomes officially important enough to act on.
The practical test will come later, when examiners apply the new approach to real banks and real mistakes rather than to policy language. If the agencies use the revised framework to sharpen expectations, remove ambiguity, and pursue only the most consequential issues while still catching dangerous trends early, the rule could end up looking like a sensible modernization. If it instead produces a more deferential posture toward bank management, it may leave the system with more paper clarity and less actual protection. That is why this announcement is drawing attention even though it is dressed up in procedural language about supervision, attention standards, and enforcement thresholds. Small changes in those categories can have outsized effects on how banks behave and how quickly regulators can intervene. And because the history of banking is full of examples where weak controls were obvious in hindsight, any move that raises the bar for intervention will be judged not by how tidy it sounds in a release, but by whether it helps catch danger before taxpayers, depositors, or the broader economy are left holding the bag.
Comments
Threaded replies, voting, and reports are live. New users still go through screening on their first approved comments.
Log in to comment
No comments yet. Be the first reasonably on-topic person here.